 Magic Heidi
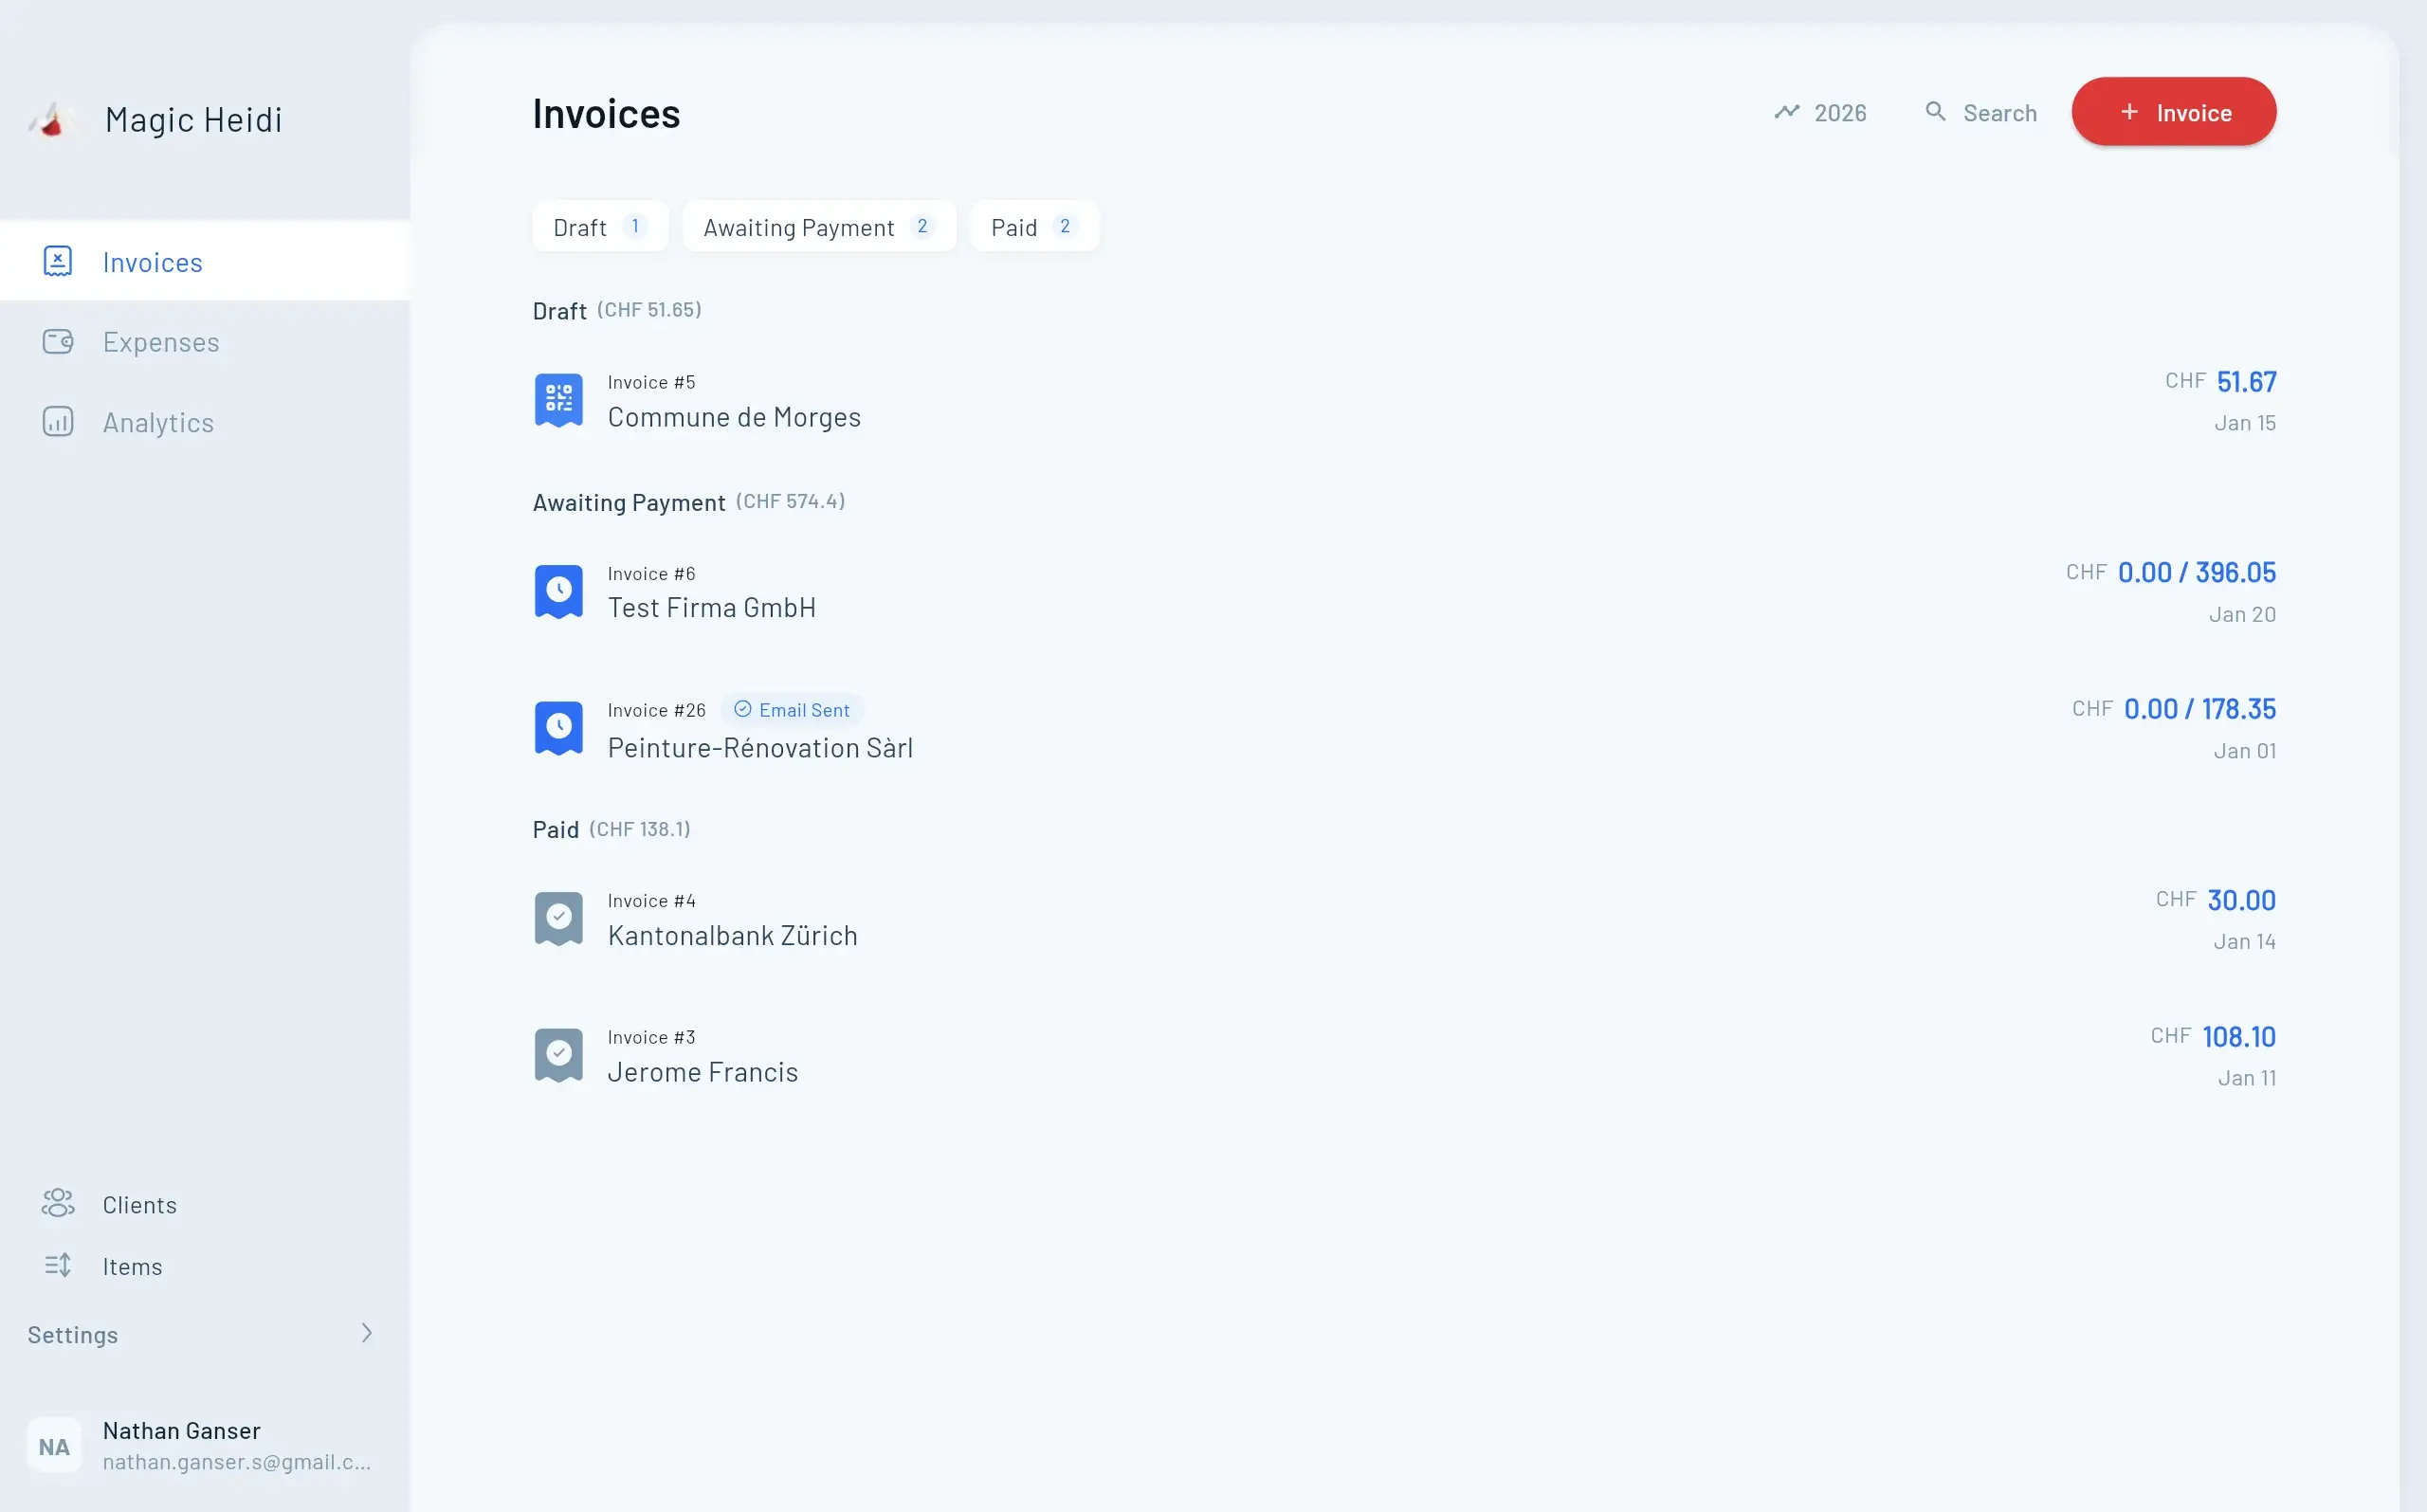
Claiming default interest in Switzerland: 5% without proof of damage
Verzugszinsen Switzerland: claim the statutory 5% per year under Art. 104 OR. Formula, VAT and a sample reminder – Magic Heidi calculates it automatically.

Founder of Magic Heidi
Your customer is behind on payment – and you're wondering whether you can claim compensation for it? Yes, you can. In Switzerland, you're entitled to the statutory default interest (Verzugszinsen) of 5% per year on late payments (Art. 104 of the Code of Obligations, OR). The best part: you don't have to prove a single franc of damage. The interest simply accrues as soon as your customer is in default. For freelancers and SMEs, this means concretely: every unpaid invoice costs your customer money – not you. Provided, of course, that you actually claim the default interest.
An example: Lena, a graphic designer from Zurich, had an open invoice of CHF 4,800.00. The customer didn't pay until 45 days after the due date. Lena calculated 4,800 × 5% × 45/365 = CHF 29.59 in default interest, correctly stated 8.1% Swiss VAT (MWST) on it – and the customer paid the interest along with the rest, without a word of objection. Why? Because it was on the reminder, properly justified with a reference to Art. 104 OR.
In this article, I'll show you exactly when default begins, how to calculate default interest step by step, how to state it on invoices and reminders – including VAT – and what you can do if the customer still doesn't pay. Plus: the other side of the coin, namely when you're the one in default.
The key points at a glance
- 5% per year – the statutory default interest under Art. 104 OR accrues without proof of damage.
- Formula: outstanding amount × 5% × days in default / 365. For CHF 4,800.00 and 45 days: CHF 29.59.
- Default begins automatically – for invoices with a calendar-based payment deadline (e.g. 30 days) without a reminder, Art. 102(2) OR.
- Without a fixed due date: only upon reminder – Art. 102(1) OR; with private customers, a friendly payment reminder is the better first step anyway.
- 8.1% VAT on default interest – if the original invoice was taxable (FTA practice).
When exactly does default begin? (Art. 102 OR)
The clock on default interest doesn't start running whenever you want it to. The Code of Obligations (OR) regulates the starting point precisely – and distinguishes between two cases.
The standard case: default without a reminder
Under Art. 102(1) OR, the debtor generally only falls into default upon receiving a reminder. BUT: paragraph 2 makes an important exception for you as the invoicing party. If you've set a calendar-determined due date on the invoice – classically "payable within 30 days", even better "payable by September 30, 2026" – your customer is already in default the moment that day expires. Without you having to send a single reminder.
The difference is subtle but important: "payable within 30 days" from the invoice date produces a determinable due date – the day after the deadline expires is the day the claim becomes due as a matter of calendar law. Practical tip: a concrete date is even safer than a deadline formula, because it leaves no room for discussion about when the period starts and public holidays.
This is why a properly drafted QR-bill with a payment deadline is your most important instrument in receivables management. If the invoice states a due date and the following day breaks, the default interest starts running. Period.
The exception: claims against consumers
Even though the law recognises automatic default: with private customers, a reminder as a first step is almost always the better choice. First, not every customer knows that a payment deadline is legally this sharp. Second, the first payment reminder is a courtesy that preserves customer relationships – the 5% default interest on CHF 850.00 after 30 days, at CHF 3.49, may be legally correct, but it's rarely worth the hassle.
In practice, this means: calculate differently for private than for business customers. With business customers and a calendar-based due date, the interest runs automatically from the day after. With private customers, the interest applies from the moment of the reminder (or the due date) – if you want interest quickly, send a reminder early; if you want to protect the customer relationship, first send a friendly reminder and only start charging interest from the second reminder onwards.
Mini-story: The carpenter and the 45 days
Beat, a carpenter in the Emmental, had built a shelf for an advertising agency for CHF 3,400.00 and written "payable within 30 days" on the invoice. Day 31: no money. Beat didn't send a reminder – he waited. After 45 days in default, he demanded the outstanding amount plus default interest in his reminder: 3,400 × 5% × 45/365 = CHF 20.96. The agency paid both. "The interest wasn't a big amount," Beat said, "but the agency understood that I take my claims seriously. They've paid on time ever since."
Calculating default interest: the formula step by step
The calculation itself is simple. It needs three ingredients: the outstanding amount, the interest rate and the days in default.
Default interest = outstanding amount × 5% × (days in default / 365)
Step by step:
- Outstanding amount: The not-yet-paid amount of your invoice. Important: the net amount without VAT – the interest is calculated on the capital owed (for a standard invoice, that's the gross amount owed – calculate with the amount your customer owes you).
- Interest rate: 5% per year, by law, Art. 104(1) OR. For 2026, unchanged: 5%. The rate has been stable for decades and is not adjusted annually.
- Days in default: Days between the due date and receipt of payment. Counted from day 1 after the payment deadline expires.
Sample calculations
| Outstanding amount | Days in default | Default interest (5%) | 8.1% VAT on it | Total interest |
|---|---|---|---|---|
| CHF 850.00 | 30 | CHF 3.49 | CHF 0.28 | CHF 3.77 |
| CHF 4,800.00 | 45 | CHF 29.59 | CHF 2.40 | CHF 31.99 |
| CHF 6,200.00 | 60 | CHF 50.96 | CHF 4.13 | CHF 55.09 |
| CHF 12,500.00 | 90 | CHF 154.11 | CHF 12.48 | CHF 166.59 |
| CHF 25,000.00 | 180 | CHF 616.44 | CHF 49.93 | CHF 666.37 |
A glance at the table shows: for small amounts, the interest is manageable. But from four-figure invoices and longer default periods, it becomes noticeable – CHF 616.44 on CHF 25,000.00 and half a year of default is a real source of income, not a trifle.
Compound interest? No – but accumulation
Default interest itself doesn't bear interest as long as the principal claim exists (a small exception under Art. 105 OR). So you're not stacking compound interest. But: the interest simply keeps running, day after day, until payment is made or the claim is collected. The longer your customer waits, the more piles up at the end – even though the slope stays linear.
Putting default interest on the reminder (including VAT)
Default interest only works if you actually claim it. The best opportunity is the reminder. Some customers only pay when it's stated in black and white what the interest costs. And: whoever states default interest correctly looks professional and legally sound.
The VAT question: 8.1% on default interest?
Yes – with one important condition. According to the practice of the FTA (the Swiss Federal Tax Administration, in its VAT info on interest), default interest is taxable if the underlying service was taxable. The reasoning: default interest is considered consideration for the provision of funds. If your original invoice was taxable at the standard rate, you also charge VAT at the standard rate on the interest – currently 8.1%. If the original service was exempt or tax-free (e.g. medical services or exports), no VAT applies to the default interest.
In practice, this means for most freelancers within the VAT registration rules for freelancers: calculate 5% interest, then add 8.1% VAT on the interest amount – not on the outstanding principal, which was already VAT-charged on the original invoice.
One important distinction here: Switzerland has no flat-rate default damages like Germany (where, e.g., a flat 40 euros is common). The FTA does not accept flat-rate default damage charges – you may not claim as damage anything that wasn't agreed. Default interest under Art. 104 OR, however, is clean and always permissible: the 5% interest plus VAT, nothing more, unless you've agreed otherwise.
Copy-and-paste text block for your reminder
The following letter is a German-language template, since Swiss business correspondence and invoices are usually written in German. Here is a block you can copy directly into your next reminder – just adjust the amounts, dates and deadlines:
Mahnung – Rechnung Nr. 2026-0417

Sehr geehrter Herr Meier

Unsere Rechnung Nr. 2026-0417 vom 15. August 2026 über
CHF 4,800.00 ist mit Zahlungsfrist vom 14. September 2026
fällig und bis heute unbezahlt.

Gemäss Art. 104 Abs. 1 OR fordern wir Verzugszinsen von 5 %
pro Jahr, berechnet auf den offenen Betrag. Bei Zahlung bis
zum 31. Oktober 2026 (45 Verzugstage) ergeben sich:

  Offener Betrag:        CHF 4,800.00
  Verzugszinsen 5 %:     CHF   29.59
  MWST 8.1 % auf Zinsen: CHF    2.40
  Total:                CHF 4,831.99

Bitte überweisen Sie den Gesamtbetrag bis zum 31. Oktober 2026
auf das angegebene Konto. Nach Ablauf dieser Frist berechnen wir
die Verzugszinsen bis zum tatsächlichen Zahlungseingang weiter
und behalten uns die Einleitung der Betreibung vor.

Freundliche Grüsse
[Ihr Name], [Ihre Firma]
Note: the days in default keep calculating dynamically until payment is actually made. That's why you should always state the figure as of a cut-off date in the reminder and announce that the interest continues to run. This way, you don't have to recalculate immediately when payment is a week late.
Mini-story: The forgotten fiduciary client
Marco, a self-employed fiduciary in Lucerne, had a client who always submitted his VAT return nice and late. On the annual fee of CHF 6,200.00, the client was regularly 60 days in default. Marco resolved to change that – and automatically added default interest to the next reminder: CHF 50.96 plus VAT, totalling CHF 55.09. The client called, puzzled about "those few francs". Marco briefly explained Art. 104 OR – and that the interest would automatically appear on the reminder for every late payment going forward. Since then, the return has been on time. Sometimes all it takes is one simple question: do you want to see these CHF 55.09 every time?
More than 5%? Agreeing on default damages and reminder fees correctly
5% is the statutory minimum interest. What if your actual damage is higher – for example, because you're paying 9% interest on a line of credit to bridge the liquidity gap?
Art. 106 OR: More only by agreement
Under Art. 106(1) OR, you can claim damage beyond what the 5% default interest covers – but you must prove it, and the debtor can exonerate themselves if no fault can be attributed to them. Important in practice: there are no flat-rate default damages like in Germany (where, e.g., a flat 40 euros is common). The FTA does not accept flat-rate default damage charges – you may not claim anything that wasn't concretely evidenced or effectively agreed. Administrative costs and reminder fees may only be passed on if they were agreed in advance in your terms and conditions (AGB) or invoice terms.
What this means for you: anyone who wants to claim default costs beyond 5% needs either provable damage (e.g. line-of-credit interest for bridging) or a pre-agreed arrangement. You'll find details on permissible fees in our article on reminder fees in Switzerland.
Sample terms-and-conditions clause
The following clause is a German-language template, since Swiss terms and conditions are typically written in German. Here is a clause you can include in your terms and conditions or invoice terms (not legal advice, but drafted for practical use):
§ Zahlungsbedingungen

Rechnungen sind gemäss Zahlungsfrist netto zur Zahlung fällig.
Bei Verzug werden Verzugszinsen von 5 % per annum gemäss
Art. 104 OR berechnet und mit 8.1 % MWST belastet, sofern die
zugrunde liegende Leistung steuerbar ist.

Pro Mahnung wird eine Mahngebühr von CHF 20.00 erhoben.
Der Nachweis eines weitergehenden Verzugsschadens (z. B.
Kontokorrentzinsen, Inkassokosten) bleibt vorbehalten und
wird auf Verlangen der Berechnung zugeführt.
Two things about handling this clause properly: first, it must have effectively come to the customer's attention – as an annex to the quote, with a reference on the invoice, or, for B2B customers, in recurring business relationships. Second, even with the clause in hand: with consumers, a friendly payment reminder before charging interest is almost always the better path – legally sound and customer-friendly at the same time.
If the customer still doesn't pay: default interest all the way to debt collection
Default interest on the reminder works with most customers. With some, it doesn't. Then begins the escalation stage: debt collection (Betreibung).
What happens to the interest during debt collection
The default interest keeps running until one of two things happens: your customer pays, or the debt collection proceedings are legally concluded (with a legal objection or a certificate of unsatisfied indebtedness). You can include the interest accrued up to that point in the debt collection request – as part of your claim, with the cut-off date stated in the form.
The debt collection office itself doesn't calculate interest for you – you provide the figure. In practice: pick a clean cut-off date shortly before the request and calculate the interest up to that day. The costs of debt collection (an advance of roughly CHF 20.00 to CHF 40.00) are borne by the debtor if the proceedings are successful – more on this in our guide on initiating debt collection.
Default doesn't end with the reminder
A common misconception: many think that with the first reminder, the default is somehow "resolved". No – the reminder is what properly starts the default (if no payment deadline was agreed), or it merely documents it. The interest simply keeps running. And that's a good thing: in a longer default spiral, this creates a clean, traceable interest trail that you claim as part of your receivable in the debt collection request.
One more note on limitation: your claim becomes time-barred after 10 years under Art. 127 OR – and the default interest follows suit. A reminder interrupts the limitation period and restarts it. So if you follow up cleanly every few years, a claim practically never becomes time-barred. This is also why a certificate of unsatisfied indebtedness from debt collection can be so valuable.
When you're in default yourself: default interest from the FTA and other creditors – and what you can do about it
Up to here, you were the creditor. Now the flip side: sometimes you're the one on the debtor side – and then you want to know what's coming your way.
Default interest from the FTA: 4% on federal taxes
The most common trap for freelancers: the VAT return. If you submit it to the FTA too late or with too little, default interest starts running – and it isn't invented by the FTA, but set annually by the Federal Department of Finance (FDF). For 2026, the default interest rate on federal duties and taxes is 4% (you'll find the current rates at the FDF). The interest is calculated on the missing amount and added to your next return – the FTA only charges interest from CHF 100.00.
How quickly does that hurt? Let's calculate: Sandro, an IT consultant in Bern, submitted his VAT return 40 days late, with CHF 3,400.00 in back payments. Default interest: 3,400 × 4% × 40/365 = CHF 14.90. Sounds harmless – but the interest runs on every return you miss, and the same principle applies to direct federal tax. Whoever has their customer deadlines under control should also have their own deadlines under control: VAT returns quarterly, deadlines in the calendar.
Contractual interest rates of other creditors
With private creditors – such as your line of credit at the bank, your leasing or suppliers with purchase-on-account – Art. 104 OR also applies: 5%, unless otherwise agreed. With banks, something else is almost always agreed: line-of-credit interest of 8 to 12% is common. So check your credit agreements before letting them run – that's often more expensive than any default interest from your customers.
One consolation: if you're unable to pay yourself, you can countersteer with an instalment payment arrangement. You'll find details in the article on agreeing an instalment payment plan. A payment deferral is also possible with the FTA – it depends on your situation and is granted upon request.
Conclusion and FAQ: enforcing default interest quickly
Default interest is an underrated instrument for freelancers in Switzerland. It's anchored in law, requires no proof of damage and can be calculated with a clear formula. The biggest effort isn't in the law, but in the process: monitoring due dates, counting days in default, stating interest correctly, accounting for VAT – on every single invoice.
This is exactly where Magic Heidi comes in. The software monitors your payment deadlines automatically, detects default, calculates the 5% default interest to the day and creates reminders including correctly stated VAT – at the push of a button, for every open invoice. You want to focus on your business, not on interest calculations? Try Magic Heidi – from CHF 25.00 per month, significantly cheaper than bexio, and you'll find all prices and packages at a glance.
Further links and sources
- Art. 102–106 OR on Fedlex – the complete provisions on default and default interest in the Code of Obligations
- FTA VAT info on interest – the FTA's practice on VAT on default interest
- Default interest rates for federal taxes at the FDF – the annually set interest rate for federal duties and taxes
This article provides general information and does not constitute legal or tax advice. For specific individual cases, consult a professional.